
As a small company director with fluctuating income the the ability to increase/decrease or suspend payments is really easy from the website or from the app.
Trevor
Penfold customer
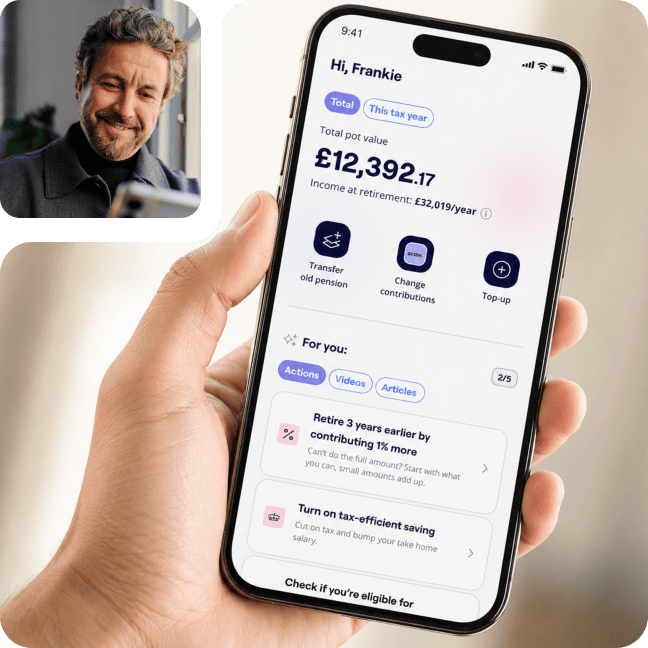
If you run your own limited company, your business can contribute directly to your pension – helping you build your retirement savings while potentially reducing your company’s Corporation Tax bill.
With Penfold, you can make company and personal contributions, bring old pensions together and manage everything from one simple app.
Your pension pot value can go up or down, but staying invested can help it grow
Running your own company gives you another way to build your retirement savings.
Make employer pension contributions directly from your limited company into your Penfold pension.
Company pension contributions can generally be treated as an allowable business expense where HMRC rules are met, potentially reducing your company’s taxable profits.
Build your pension using company contributions, personal contributions or a combination of both.
Transfer eligible old pensions to Penfold and manage your retirement savings in one place.

As a limited company director, your business can make employer contributions directly into your pension.
Unlike personal pension contributions, company contributions are made directly from your business and don’t usually require you to take the money as personal income first.
With Penfold, you can make company contributions whenever it works for your business – whether that’s regularly throughout the year or as individual contributions when you choose.
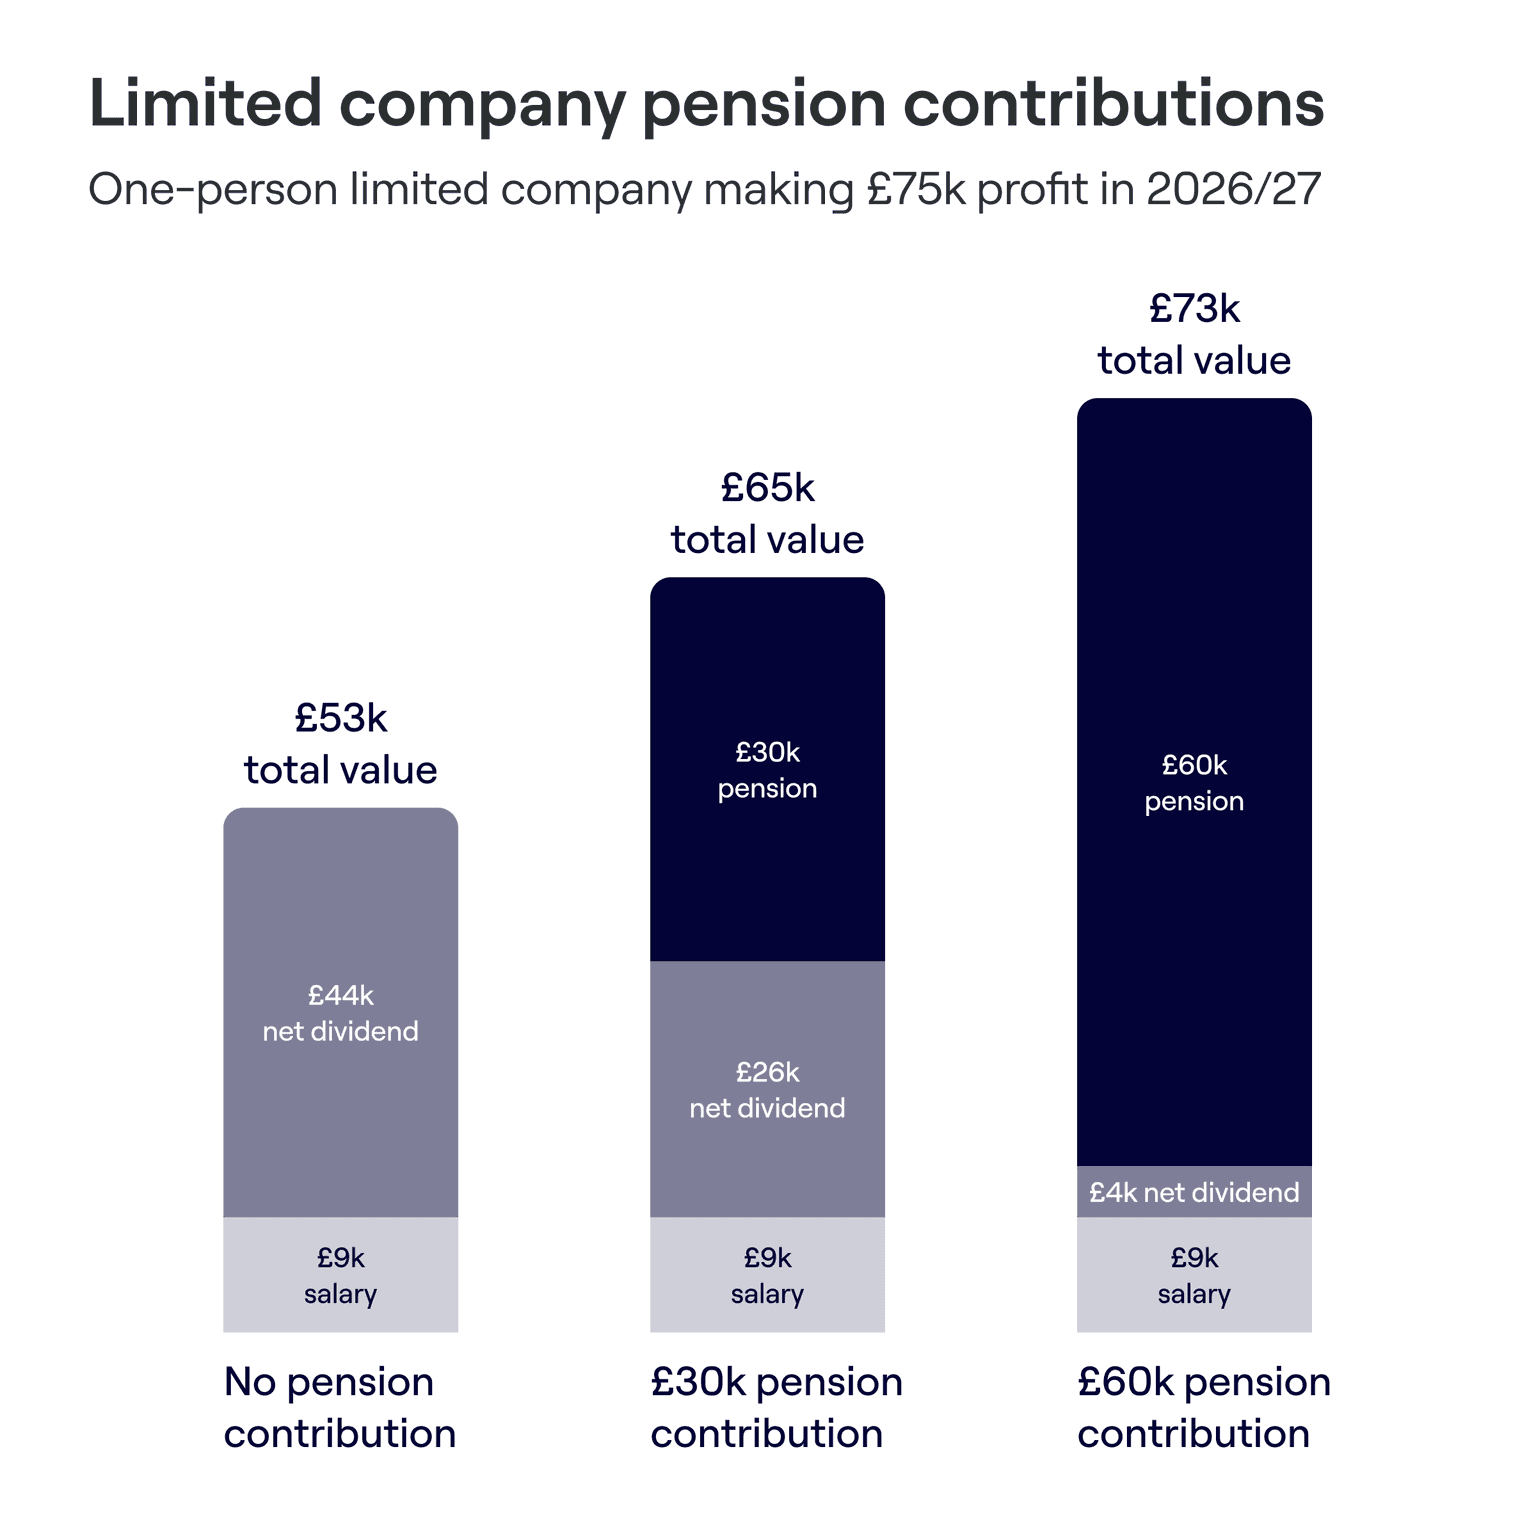
Eligible pension contributions made by your limited company can generally be treated as a business expense, potentially reducing the profits your company pays Corporation Tax on.
For example, a £10,000 eligible company pension contribution could reduce taxable company profits by £10,000. The Corporation Tax saving depends on your company’s circumstances and the rate it pays.
The full £10,000 contribution instead goes into your pension.
Tax treatment depends on your and your company’s individual circumstances and may change. Company pension contributions must meet HMRC requirements to receive Corporation Tax relief.
Running a company doesn’t mean you have to choose one way to fund your pension. With Penfold, you can make contributions from your limited company, make personal contributions yourself, or use a combination of the two.
That gives you flexibility to build your pension around both your personal finances and your business.
Your limited company pays directly into your pension. Eligible contributions may be deductible when calculating taxable company profits.
Pay into your pension personally and Penfold will automatically claim eligible basic-rate tax relief from HMRC.
Use a combination as your circumstances change.
Running your own company today doesn’t mean you’ve always worked for yourself.
If you’ve built up pensions from previous jobs, you can request to transfer eligible pensions to Penfold and manage them alongside the pension you’re building through your company.
We’ll help you find old pensions, contact providers and manage the transfer process. That means fewer pensions to keep track of and a clearer picture of what you’ve built for retirement.
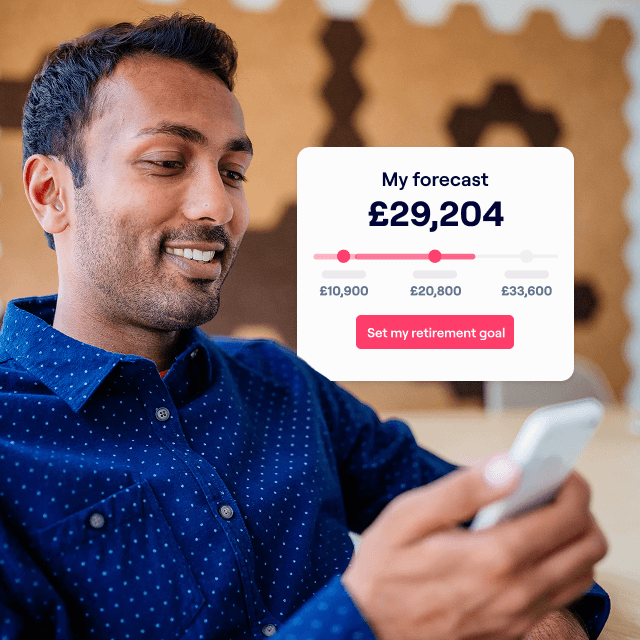
See more than just your pension balance.
Penfold helps you understand what you’re building towards and what your current savings could mean for retirement.
See how much you’ve saved, keep track of contributions from you and your company, explore your projected retirement income and understand how changing your contributions could affect your future.
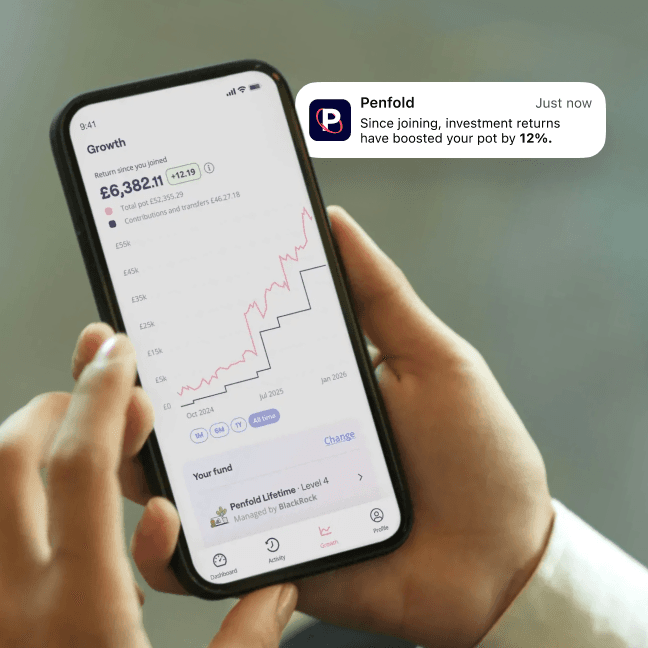
Your Penfold pension is a Self-Invested Personal Pension (SIPP) with a choice of professionally managed investment options.
Our default investment approach is designed to adapt as you move towards retirement – focusing on long-term growth when retirement is further away before gradually reducing investment risk as it gets closer.
Want more choice? Explore our wider fund selection, including options designed around different attitudes to risk, sustainability and Sharia investing.
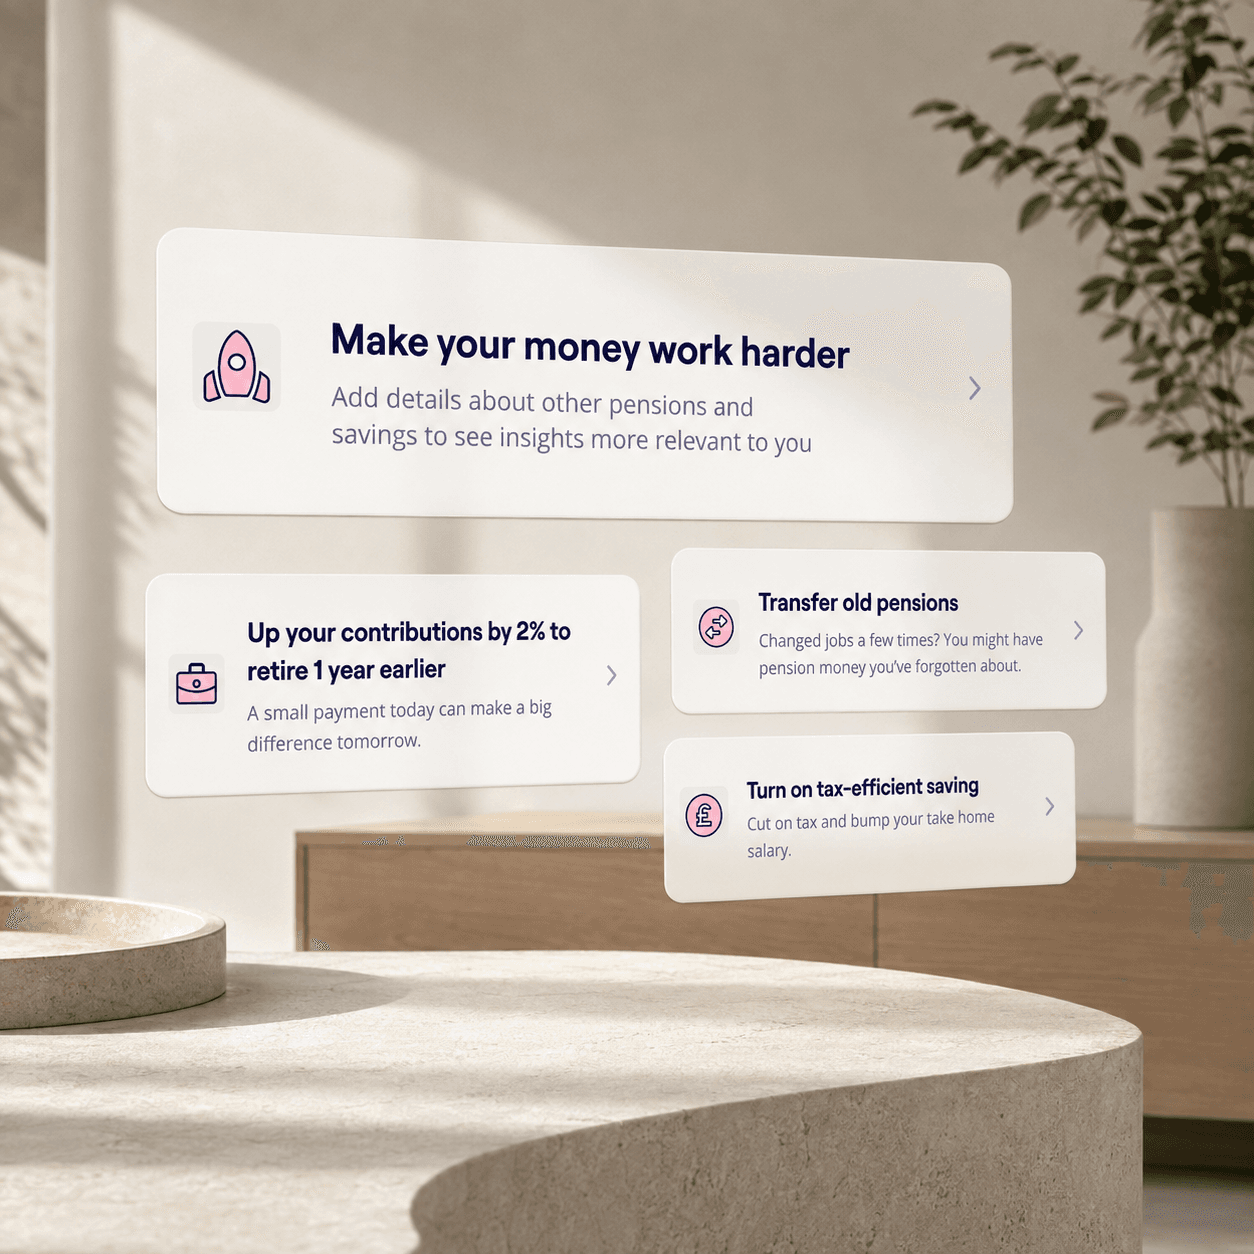
Running your company is complicated enough. Your pension doesn’t need to be.
Penfold gives you tools, information and personalised guidance to help you understand your pension and make informed decisions about retirement.
Explore whether you’re on track, understand what different contribution levels could mean for your future and get support when you need it.
Our Customer Support team is also here to help with questions about your Penfold pension, company contributions and transfers.

Keep your retirement savings within easy reach. With the Penfold app you can:
Your accountant can help you understand how pension contributions fit into your company’s finances and tax position.
And if you’d like to use Penfold, they can work with us too. We work with hundreds of accountants across the UK to help their director clients set up and contribute to pensions with Penfold.
Already arrange your pension through your accountant? Share Penfold with them and they can find out how we work with accountants and their director clients.
As a small company director with fluctuating income the the ability to increase/decrease or suspend payments is really easy from the website or from the app.
Really impressed and grateful for an easy solution for a director of a limited company to set up a pension plan.
Opened a company director pension just over a year ago. Very straightforward to use and top up and great performance so far.
Excellent digital pension app, easy to use and simple to track pension pots. Have used for director pensions so really versatile for personal and business use!
Really straight forward, and easy to set up. Perfect for a small Ltd. company like myself.
Being self-employed as an IT contractor, it's so easy to forget about my pension all together because it often just feels like so much hard work to get it setup and make payments. Penfold make it super simple and easy.
So glad I found Penfold. They have consolidated my previous pensions and got me on track to save for my future. Lovely customer service and great piece of mind for a freelancer! Highly recommend.
Very simple app allows me to manage how much I add to my pension month by month which as a freelancer is invaluable.
Pay directly into your pension from your limited company.
Eligible company contributions can reduce taxable company profits.
Contribute personally, through your company or use both.
Consolidate eligible old pensions into one place.
Use Penfold Lifetime or choose from our wider investment range.
See what you’re building towards and how changes could affect your future.


Your company isn’t just something you’re building for today. It can help you build towards your future too.
Make pension contributions directly from your limited company, contribute personally when you want to, and keep your retirement savings together with Penfold.


